The State Bank of Pakistan (SBP) has scheduled the pilot launch of the Pakistan Express Clearing System (PECS) for October 15, 2026, aiming to process cheques through electronic images captured by banks rather than moving the physical instruments through the clearing chain. The initial rollout will involve selected financial institutions, with nationwide implementation targeted for April 30, 2027.
SBP announced the programme in DI\&SD Circular No. 02 of 2026, issued on October 5. The announcement sets out a change in how banks process cheques behind the scenes. It does not mean every branch will offer the new service on October 15, or that cheque deposits will become instant.
What is the Pakistan Express Clearing System?
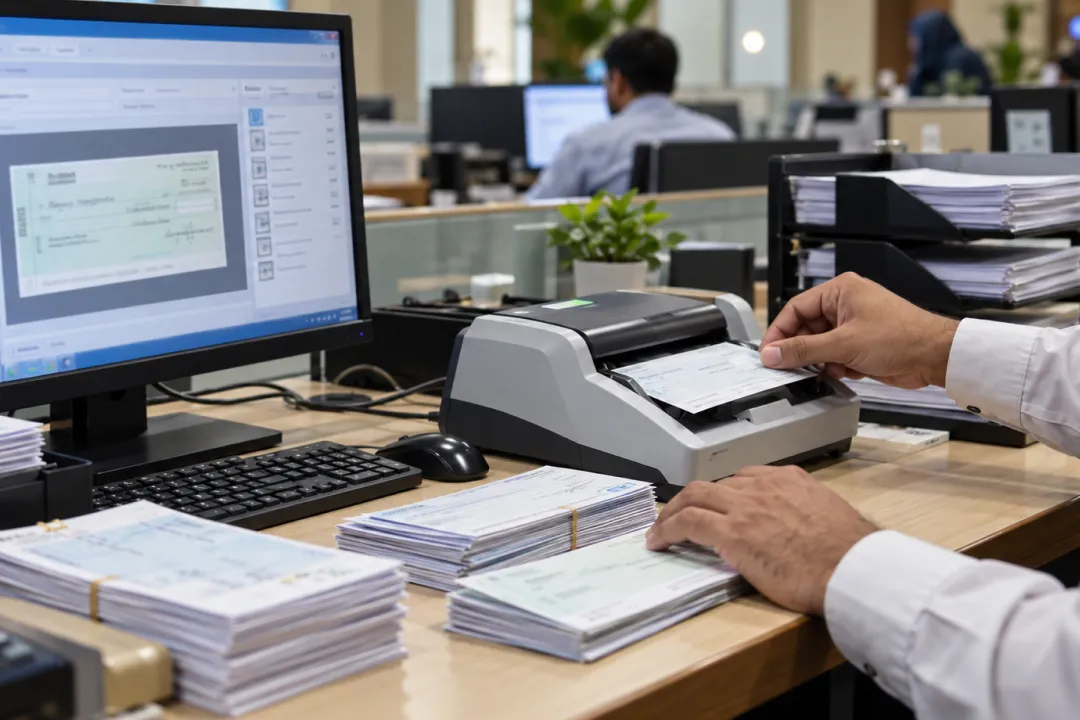
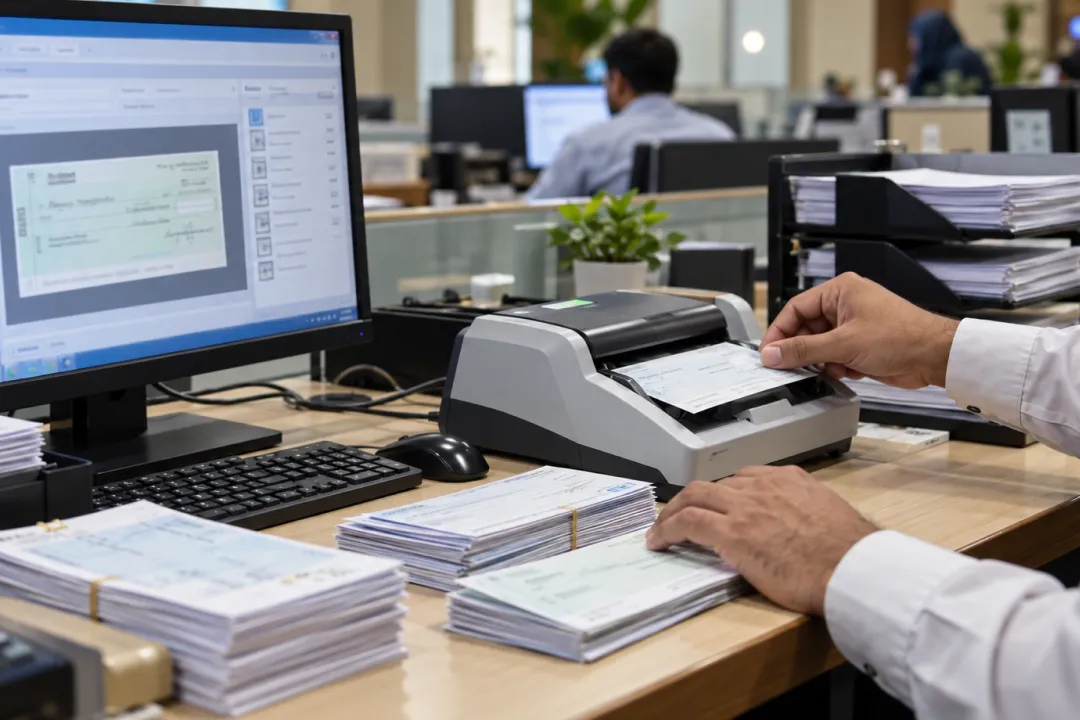
PECS is a cheque-truncation arrangement. In practical terms, truncation means stopping the physical movement of a cheque at an earlier point in the clearing process and using an electronic image and associated data for the remaining steps.
Under SBP's specified workflow, the bank that receives the cheque, known as the presenting or collecting bank, captures its image and sends it to the clearing house, NIFT. NIFT transmits the information to the paying or drawing bank for processing. The system is intended to make interbank cheque clearing more efficient by reducing reliance on transporting paper instruments.
A customer may still need to present a physical cheque through the bank's supported process. The circular does not introduce a general right to photograph a cheque at home and deposit it through any mobile banking app.
How PECS digital cheque clearing will work
- Cheque presentation: A cheque is received by a participating collecting bank through its supported channel.
- Image capture: The collecting bank captures the cheque image and the information needed for clearing.
- Clearing-house transmission: The image and associated information are sent to NIFT for onward transmission.
- Paying-bank processing: The bank on which the cheque is drawn processes the electronic information under the applicable clearing rules.
This describes the arrangement in the SBP circular. It does not establish a particular time by which a customer's account will be credited; that depends on the applicable cycle, bank processes and any required checks.
PECS launch timeline: pilot first, nationwide rollout later
The State Bank has set October 15 as the start of implementation on a pilot basis. Associated Press of Pakistan (APP), reporting details from the implementation plan, describes three stages:
| Stage | Scheduled period | Planned scope |
|---|---|---|
| Initial pilot | October 15–November 15, 2026 | Selected clearing-house participants; pilot results and readiness to be reviewed. |
| Expanded participation | November 16–December 31, 2026 | Extension to remaining clearing-house members, with branch capabilities expanded progressively. |
| Nationwide target | By April 30, 2027 | Planned nationwide implementation across the participating clearing system. |
The schedule names October 15 as the intended pilot start. These dates describe the announced implementation plan; they do not independently establish that the pilot began on time or that any stage has been completed.
APP also reports that an additional daily PECS clearing cycle is planned during the October 15–December 31 rollout period, with clearing-house submission to SBP by 3 p.m. That time concerns a clearing-system process and is not a guarantee that customers will receive cheque proceeds by 3 p.m.
What will change for bank customers?
The main immediate change is operational: participating banks should be able to process cheque images without sending the original paper cheque through all the stages previously required. That could reduce handling and transportation and support quicker processing once the system is in place.
However, customers should not assume that the pilot will be available at every bank or branch, that existing cheque-deposit instructions have changed, or that the funds will arrive instantly. SBP has directed financial institutions to train relevant staff and create public awareness, but the circular does not publish a complete consumer-facing list of pilot banks or guaranteed settlement times.
Until their bank provides specific instructions, cheque users should follow their bank's existing deposit and clearing procedure and confirm when the new arrangement becomes available at their branch.
Pakistan already had image-based cheque clearing before PECS
PECS is an upgrade in the way digital cheque clearing is carried out, not the first use of cheque images in Pakistan. NIFT says image-based clearing began in the Karachi region in September 2021, with expansion to other cities planned.
Under an earlier arrangement described by NIFT, physical cheques could be collected from banks and scanned at NIFT processing centres, while paying banks reviewed the images electronically. NIFT also described a later stage in which collecting banks would capture the images themselves, reducing the movement of original instruments.
The PECS directive formalises a rollout centred on that collecting-bank truncation model, with an SBP-set timetable for pilot testing, expansion and nationwide coverage. That is a more precise description than calling PECS Pakistan's first digital cheque-clearing service.
How is PECS different from Raast and ordinary digital transfers?
PECS deals with clearing cheques drawn on bank accounts. It does not replace the cheque with a direct app-to-app transfer, nor does it replace Pakistan's existing digital transfer systems. The electronic part of PECS concerns the processing of a cheque image and related clearing data.
The announcement comes as Pakistan's formal payment channels are becoming increasingly digital. Origin Pakistan has separately reported on SBP figures showing 13.2 billion digital retail transactions in FY26. That broader growth is context for the policy, not evidence that cheque clearing under PECS is already instantaneous.
What has not been confirmed?
Several practical questions remain unanswered by the publicly reviewed announcement:
- The complete list of banks and branches taking part in the first pilot.
- A guaranteed clearing or crediting time for individual customers.
- Whether any new customer-facing mobile cheque-deposit option will be offered.
- Whether existing customer charges will change.
- The operational results of the pilot and the timing of availability at each individual branch.
SBP has circulated implementation rules and operating instructions to clearing-house members, but the detailed annexes were not independently reviewed for this report. This article therefore does not make claims about security procedures, fees or consumer rights beyond the information established in the circular and attributed reporting.
What happens next?
The next milestone is the pilot scheduled for October 15. Participating institutions and NIFT are expected to review its results before the broader expansion phase. SBP's target remains nationwide coverage by April 30, 2027.
For customers, the most useful confirmation will come from their own bank: whether their branch is using PECS, how cheques should be presented and what clearing times apply. Until those details are issued, PECS should be understood as a phased upgrade to cheque-clearing infrastructure rather than a promise of instant payment.